Every commodity analyst with a microphone lost their mind the moment headlines flashed that Washington was courting Alexander Lukashenko for a massive fertilizer arrangement. The lazy consensus hit the financial wires instantly: Canadian agricultural dominance is crumbling, Saskatchewan is about to lose its primary export lifeline, and a resurrected Belaruskali is flooding the American Midwest with cheap, sanctions-busted mineral wealth.
It is a neat, terrifying narrative for anyone holding stock in Canpotex or living in Regina. It is also entirely detached from physical reality. Meanwhile, you can find similar events here: The Anatomy of Economic Friction: Quantifying Illness and Caregiving Losses.
I have spent years watching market participants confuse political theater with supply chain execution. When politicians posture about trade routes, amateur observers look at maps and draw straight lines. Professionals look at rail bottlenecks, port handling tariffs, long-term binding off-take agreements, and chemistry. If you run the actual numbers on this so-called tectonic shift, the entire Belarus potash panic evaporates into thin air.
The Geography of Delusion
Let us start with basic logistics, a subject that modern commentators treat as an optional elective. To explore the complete picture, check out the recent report by CNBC.
The United States imports nearly all of its potash fertilizer, and roughly eighty percent of that volume crosses a shared, frictionless border from Saskatchewan. Trains load up at massive, highly automated mines operated by giants like Nutrien and Mosaic, roll across the 49th parallel, and drop product directly into the heart of the American agricultural belt. The transit economics are brutally efficient. Short rail lines, minimal handoffs, integrated North American rail networks.
Now, look at the alternative being peddled by headline-chasers. Belarus is landlocked. For decades, its primary export valve for potash was the port of Klaipėda in Lithuania. That valve was slammed shut by Vilnius and European sanctions enforcement.
To get Belarusian muriate of potash to New Orleans or any other American port today, what actually happens? The product has to be loaded onto rail cars in Salihorsk, hauled thousands of miles eastward across Russian territory, transferred to Russian Baltic ports like Bronka, loaded onto ocean-going vessels, shipped across the Atlantic Ocean, and finally offloaded onto barges or trucks in the United States.
Anyone who thinks you can pipe mineral freight across two sanctioned empires, pay double-handling fees at congested Russian terminals, absorb transatlantic shipping rates, and undercut Canadian rail delivery by even a single penny has never managed a supply chain in their life. Distance matters. Handling touchpoints matter. Every time a bulk commodity changes modes of transport—from train to port silo, from port silo to ship hold, from ship hold to barge—margin bleeds out. Belarusian potash delivered to the American Gulf Coast is not a discount; it is an expensive logistical exercise driven by spite, not economics.
The Phantom Volume Myth
Even if we pretend that shipping costs defy the laws of gravity and freight economics, we slam into a second, insurmountable wall: there is nothing left to buy.
The media narrative treats Belaruskali as an open spigot waiting for an American hand to turn the valve. Listen to what Lukashenko himself stated when asked about exporting to Western markets: the volume simply does not exist.
Ever since traditional Western doors slammed shut following the 2021 designations, Minsk did not sit around waiting for a diplomatic thaw. They pivoted hard. They re-routed their supply chains eastward and southward. Today, the vast majority of Belarusian potash output is locked up under rigid, multi-year, long-term binding contracts with buyers in China, India, and Brazil.
Commodity markets do not operate like a clearance rack at a liquidation center. You cannot simply walk up to a producer, snap your fingers, and redirect millions of tonnes of industrial fertilizer that are already legally bound to Asian and South American agricultural conglomerates. Belaruskali’s production capacity is fully subscribed. To supply the United States in any meaningful quantity, Belarus would have to default on its existing contractual obligations to Beijing and New Delhi.
Imagine a scenario where Minsk attempts to break these Asian contracts to chase American buyers. They would instantly alienate their primary financial lifelines, invite severe logistical retaliation from Moscow—which controls their export railways—and destabilize the exact commercial alliances that kept their regime afloat during peak Western isolation. It is a non-starter. The tonnage does not exist on the open market. A single token 30,000-tonne trial cargo arriving at a Gulf port is not a market disruption; it is a photo op designed to juice a press cycle.
The Grade and Quality Mismatch
Let us dig deeper into the physical product itself, because all potash is not created equal, despite what financial reporters assume.
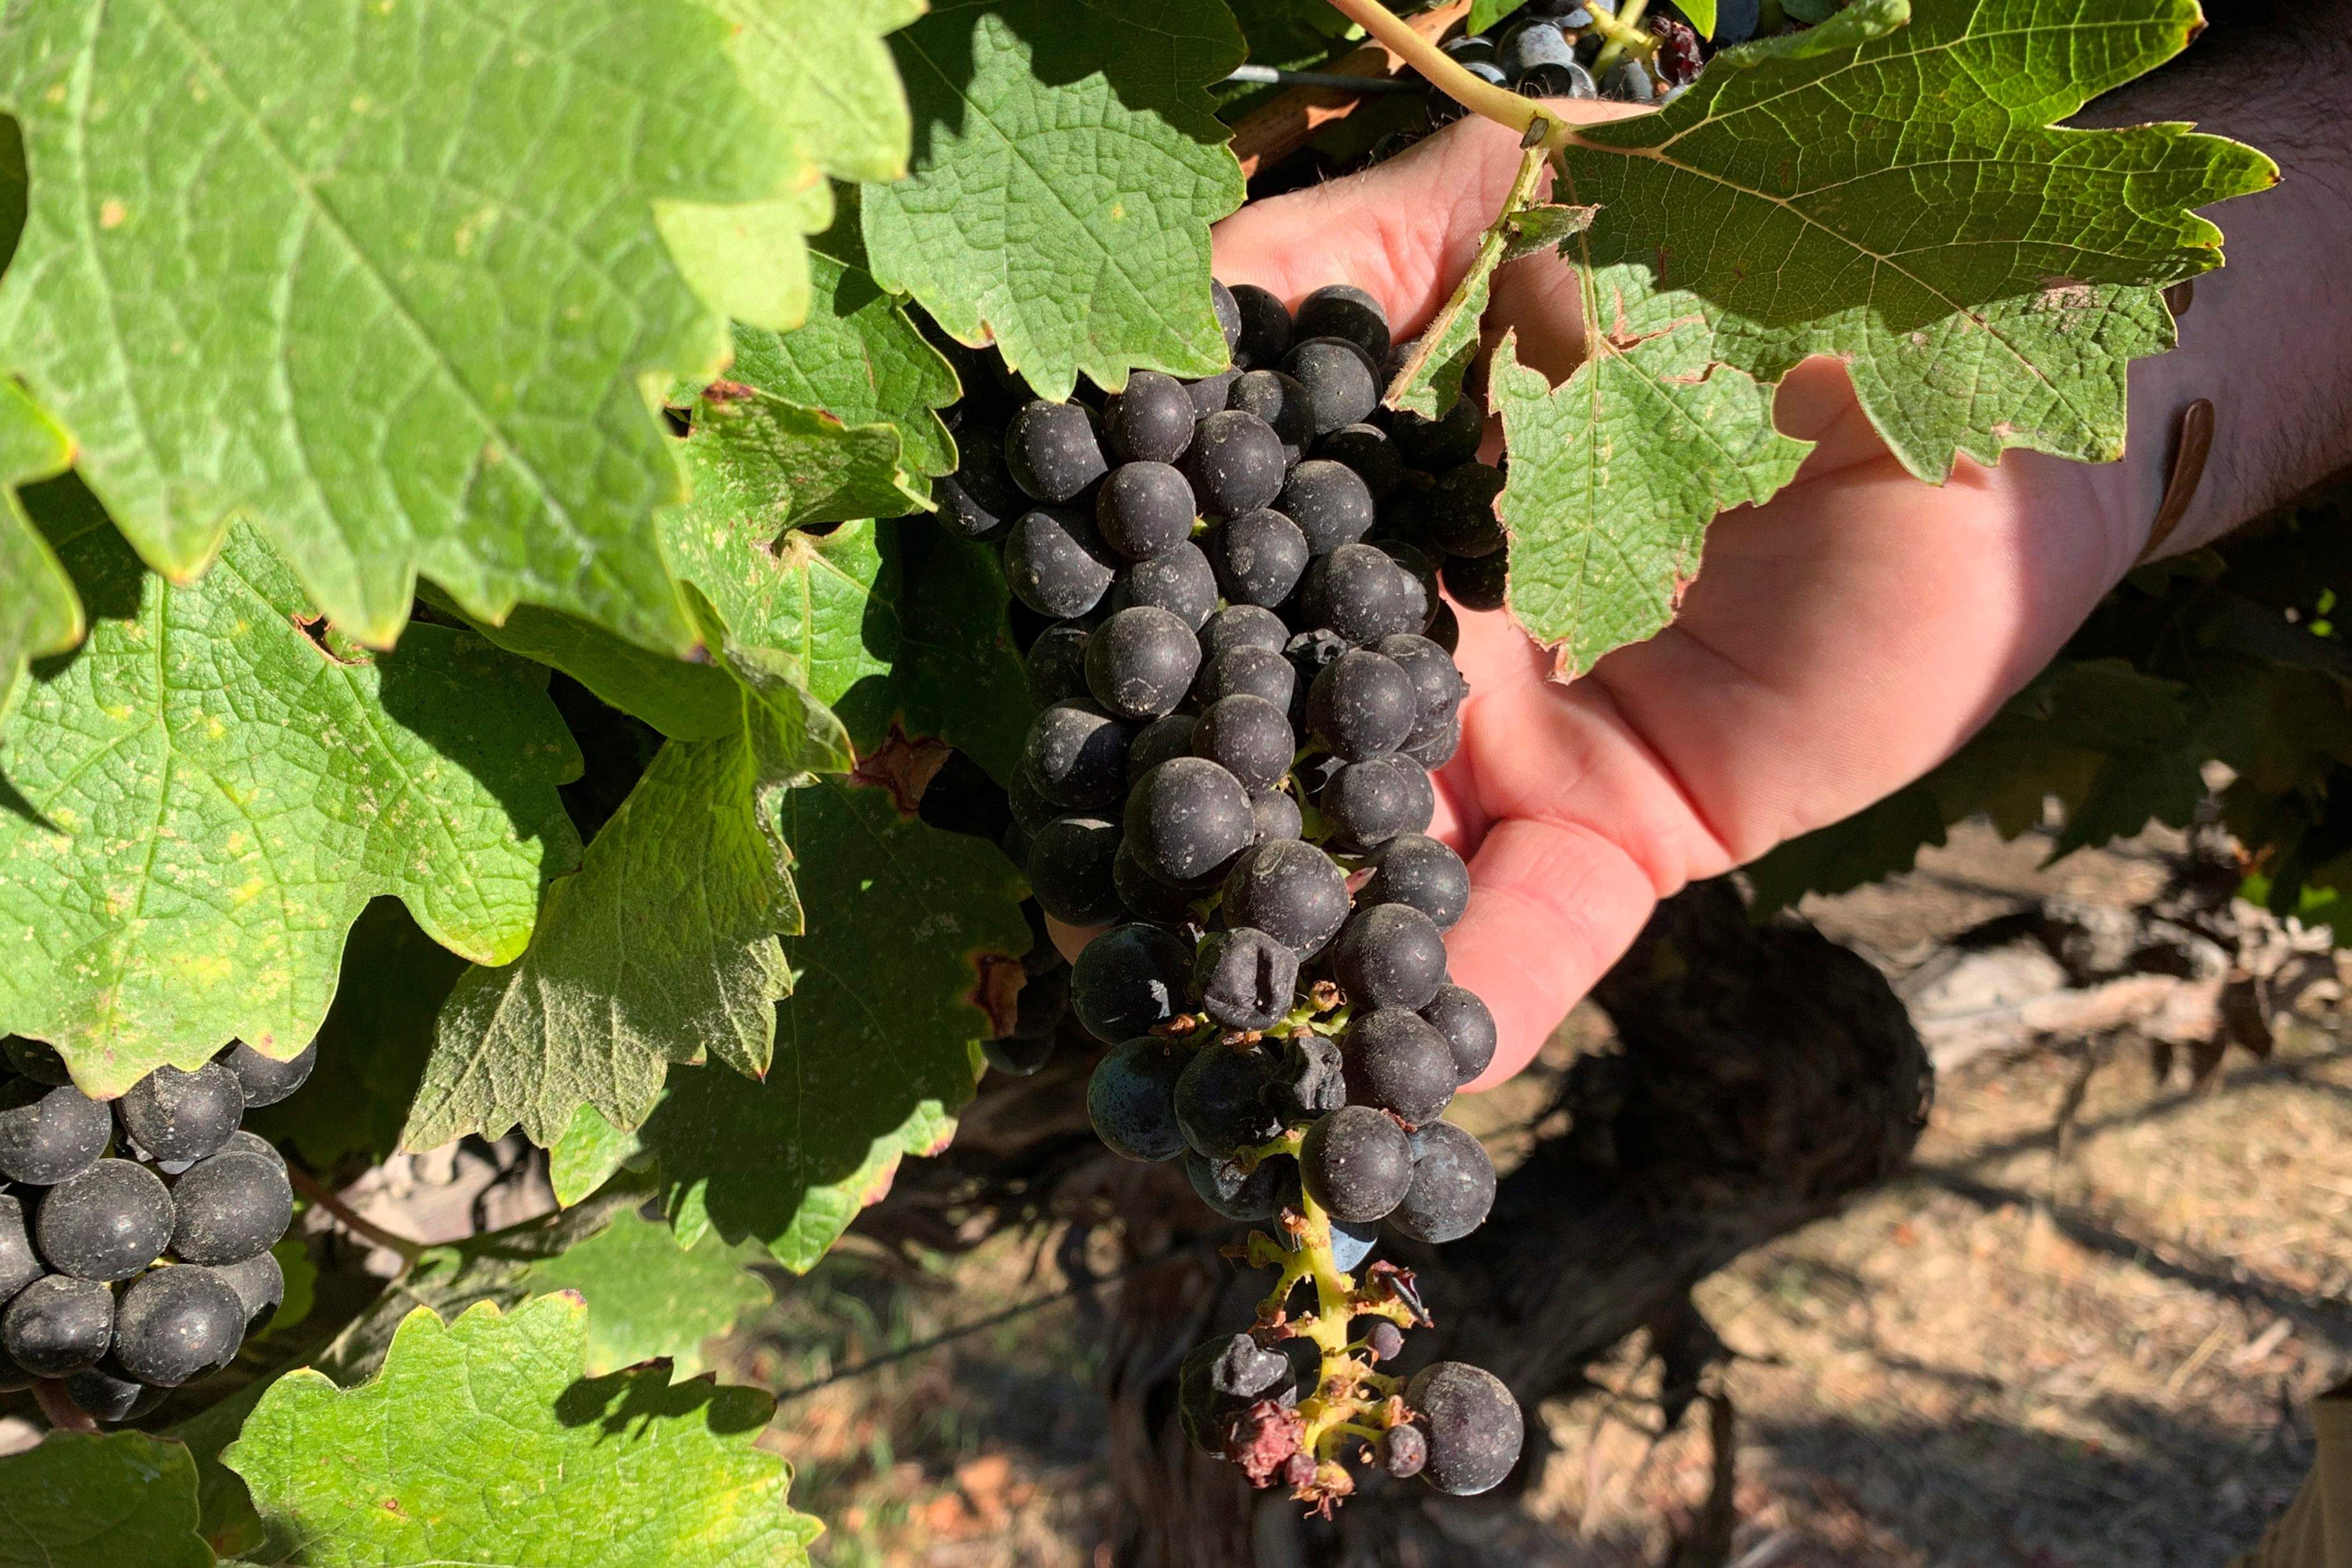
Potash is shorthand for potassium-bearing minerals, predominantly muriate of potash (MOP). But the physical characteristics dictate where and how it can be applied. Belaruskali primarily produces pink potash. The geological composition of the Starobin deposit yields a distinct pinkish hue due to iron oxide impurities embedded within the crystal lattice.
The North American agricultural market relies heavily on white standard and granular MOP, or specific processed grades tailored to high-efficiency blending facilities across the Midwest. While agronomists will tell you that the potassium content ($K_2O$) is chemically comparable once dissolved, blending plants, specific soil chemistries, and industrial fertilizer manufacturers prefer uniformity. Re-tooling supply chains for aesthetic or minor impurity differences adds friction. When farmers are paying top dollar for blended NPK (Nitrogen, Phosphorus, Potassium) formulas, they optimize for predictable blending behavior, not political statements.
The Sanctions Mirage and the Financial Freeze
We also need to dismantle the naive view of how sanctions relief actually functions. Following the issuance of specific U.S. Treasury Office of Foreign Assets Control general licenses, some administrative barriers were lowered, and small transactions trickled back. Minsk immediately weaponized this diplomatic opening to demand the release of tens of millions of dollars in frozen banking funds sitting in U.S. institutions.
This is not a trade policy; it is a hostage negotiation executed via balance sheets.
Minsk wants its frozen liquidity back, and Washington wants pre-midterm political messaging that signals toughness on traditional allies while dangling the prospect of lower input costs to domestic farm lobbies. It is political theater dressed up as international trade policy. The moment the cameras turn off, the hard math of rail gauges, shipping insurance through Russian Baltic ports, and maritime freight rates reasserts itself.
Insurance underwriters alone make this trade a compliance nightmare. Shipping cargo originating from a sanctioned-adjacent Belarusian entity, moving across Russian rail networks, and loading onto vessels via Russian ports triggers every compliance alarm at every major marine insurance house in London and New York. The cost of risk mitigation, compliance audits, and legal clearance eats away any theoretical price advantage before the cargo even clears territorial waters.
Why Canada Holds the Royal Flush
While pundits hyperventilate over Washington flirting with Minsk, they fundamentally misunderstand the structural security of the North American fertilizer complex.
Canada is not a vulnerable supplier; it is an irreplaceable resource superpower in this specific sector. Saskatchewan holds nearly half of the world's known potash reserves. The mines are world-class, massive, and environmentally regulated under stable legal frameworks. More importantly, the logistics are baked into the geography of the continent.
Nutrien and Mosaic do not need to worry about Baltic choke points, Russian rail tariffs, or European Union secondary sanctions. They load cars directly onto the Canadian National and Canadian Pacific rail networks, feeding terminals straight into Iowa, Illinois, and Nebraska.
When industry analysts look at fertilizer risk, they know that potash is historically the least of a farmer's worries. As leading market specialists point out, North America has never struggled to source abundant potash. The real systemic vulnerabilities in Western agriculture have always been nitrogen and phosphate—nutrients exposed to natural gas price shocks and concentrated phosphate mining constraints in places like Florida and Morocco. Potash has always been the stable, abundant anchor of the trio. Trying to manufacture a supply crisis in potash by looking to landlocked Eastern European producers is like trying to solve a localized traffic jam by importing cars from the moon.
The Real Agenda Nobody Is Talking About
If the Belarus potash deal makes no economic sense, why is it dominating the news cycle?
Because leverage in modern trade negotiations is rarely about the commodity named in the press release. It is a pressure tactic. By publicly entertaining a pariah state's mineral exports, Washington sends a sharp, unmistakable signal to Ottawa during broader trade and sovereignty friction. It is a high-visibility warning shot designed to alter behavior on entirely unrelated files, from defense spending commitments to border security and cross-border trade pacts.
It is a classic diplomatic feint. It creates maximum noise in the media while changing precisely zero structural realities on the ground in the agricultural sector.
Stop Falling for the Headline Trap
If you are an agricultural producer, an investor, or a supply chain strategist, stop reacting to every geopolitical trial balloon that floats out of a press briefing.
Do not reallocate capital based on phantom tonnage that is already locked up in Chinese warehouses. Do not bet against the structural gravity of Saskatchewan rail economics. And above all, do not mistake a diplomatic pressure tactic for a functioning commercial market.
The Belarus potash deal is a ghost. It cannot scale, it cannot compete on price once real logistics are tallied, and it relies on a supply chain that runs straight through the heart of geopolitical volatility. Canada’s potash monopoly is entirely safe because no amount of political rhetoric can rewrite the map.