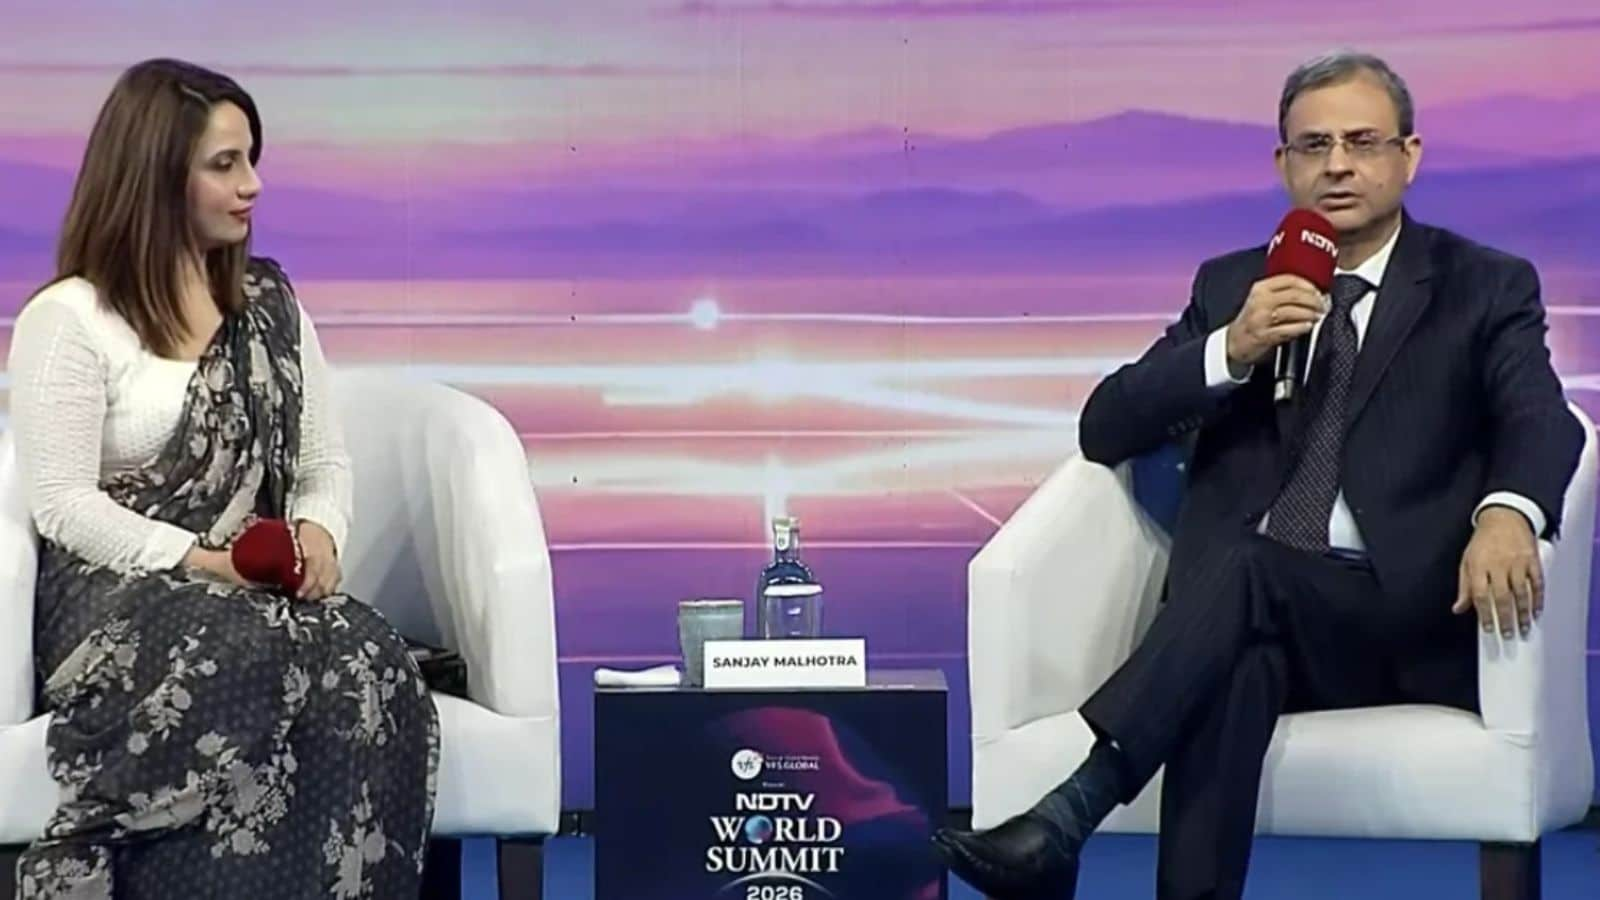
The financial press loves a good corporate soap opera. For months, commentators have hyperventilated over whether Tata Sons will bow to regulatory pressure, shed its upper-layer non-banking financial company status, and rush into an initial public offering. When the Reserve Bank of India governor recently faced questions on the matter, he did what bureaucrats do best. He pointed at the rulebook.
Cue the collective groan from market analysts. They wanted a scoop. They wanted policy exceptions. They wanted a dramatic clash between state authority and corporate royalty.
Instead, they got dry statutory adherence. And that is precisely why the financial media completely missed the point.
The lazy consensus in the market argues that forcing a sprawling conglomerate into public markets democratizes ownership and unlocks hidden value. This view treats stock exchanges like mandatory finishing schools for private giants. If you grow big enough, the argument goes, you owe the public a ticker symbol.
This perspective is fundamentally flawed. It misunderstands the entire purpose of systemic banking regulations and romanticizes public listings as an unalloyed good.
Let us look at the mechanics of what an upper-layer classification actually means. Under current central bank guidelines, certain large non-banking entities must list their shares within a specified timeframe due to their systemic footprint. The rule exists to ensure transparency, market discipline, and liquidity in firms whose failure could send shockwaves through the broader economy. It is a prudential safeguard. It is not an invitation for retail speculators to chase conglomerate hype.
Tata Sons sits at the apex of a multi-billion-dollar empire spanning steel, software, automotive, and aviation industries. The holding company model relies on cross-holdings, patient capital, and a long-term strategic horizon that routinely clashes with quarterly earnings pressures. Public markets are notoriously impatient. They punish strategic investments that take a decade to bear fruit. They demand predictable linear growth from businesses that operate in cyclical, high-risk sectors.
Forcing a core investment company of this magnitude onto the public ledger introduces systemic volatility where stability is required. When a holding company's valuation becomes hostage to day-to-day market sentiment, its ability to act as a financial shock absorber for its operating subsidiaries weakens. If Tata Sons faces pressure to maximize short-term share price performance, its capacity to bail out an underperforming manufacturing unit or fund a multi-year deep-tech pivot evaporates.
Critics argue that maintaining private status while holding massive financial assets creates an unfair regulatory loophole. They claim investors are missing out on the value trapped inside the conglomerate. This argument prioritizes the desires of portfolio managers over macroeconomic stability.
Public markets are already flooded with subsidiary options. Investors wanting exposure to the crown jewels of the group can easily buy shares in Tata Consultancy Services, Tata Motors, Titan, or Tata Power. The idea that retail investors are somehow starved of access to the brand's growth is an illusion manufactured by investment bankers eager for massive IPO underwriting fees. An IPO for the holding company would primarily generate liquidity for secondary shareholders and hefty commissions for wall street intermediaries, adding very little genuine economic productivity.
The central bank's stance is not about stifling capitalism. It is about risk containment. When regulators design frameworks for systemically important institutions, their job is to prevent contagion, not to satisfy the cravings of day traders looking for the next big pop.
We have seen this movie before. Whenever regulators enforce strict boundaries, financial engineers immediately look for workarounds. Suggestions have ranged from debt restructuring to asset stripping just to dodge the listing mandate. These maneuvers miss the deeper reality. Compliance should not be a game of regulatory chess where the objective is to find loopholes. It should be an alignment with structural intent.
If the rules state that large financial layers must be transparent and publicly accountable, then conglomerates face a binary choice. They can restructure their balance sheets to slip below the systemic threshold, or they can accept the oversight that comes with the territory. What they should not expect is a bespoke exemption carved out of respect for their historical prestige.
The financial establishment finds this rigidity uncomfortable. We live in an era where size and influence are routinely expected to bend bureaucratic frameworks. Yet, systemic risk does not care about brand equity or philanthropic legacy. A bad debt default or a liquidity crunch in a major core investment company ripples through the banking sector with identical severity regardless of whether the controlling family name carries historical weight.
Markets function best when rules apply uniformly. The moment regulators start granting dispensations based on corporate pedigree, the entire framework loses credibility.
Investors crying foul over missed listing gains need to recalibrate their expectations. A conglomerate holding structure is designed to insulate operating units from market noise, not amplify it. Stripping away that insulation for the sake of public market liquidity destroys the very mechanism that makes long-term industrial planning possible in developing economies.
The central bank did not dodge the question by reading the rulebook. It answered it in the only language that matters. Regulations are not negotiating points. Stop treating systemic safeguards like minor inconveniences to be lobbied away.