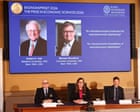
Celebratory headlines about "smoothing crises" miss the point. They treat economic pain like a bad hair day that a little styling gel can fix. It isn't.
When a headline hails Nobel laureates Robert Hall and Michael Woodford for teaching policymakers how to smooth out economic shocks, the lazy consensus rushes to applause. The story usually goes like this: markets get jittery, output wobbles, and smart economists hand central bankers and treasuries a dial to turn down the turbulence. Lower volatility. Fewer sleepless nights. A gentler ride. Meanwhile, you can explore related events here: The Economics of Capital Raiding Why Green Subsidies Fail Structural Tests.
That story is comforting. It is also dangerously incomplete.
Smoothing a crisis does not erase the underlying imbalance that caused it. Often, it just stretches the bill out over more years, hides the rot behind calmer quarterly numbers, and trains every borrower, bank, and boardroom on Earth to expect a cushion every time the floor starts to shake. To see the complete picture, check out the excellent report by Bloomberg.
If you want to understand what real macro stabilization does—and where the popular "smoothing" narrative breaks down—you have to stop asking how we make downturns feel softer and start asking what happens to incentives, balance sheets, and truth itself when pain gets postponed.
The Lazy Consensus Around "Smoothing"
Most commentary on crisis smoothing relies on a simple assumption: volatility is inherently bad, and stability is inherently good. Keep GDP growing on a neat line. Keep credit flowing. Keep unemployment from spiking. If policy interventions flatten the troughs, everyone wins.
That assumption confuses symptoms with causes. A recession or financial crunch is rarely just bad luck falling out of a clear sky. Frequently, it is the delayed reckoning for years of misallocated capital, cheap leverage, sloppy underwriting, or rigid prices that no longer match reality.
When policymakers step in aggressively to smooth every bump, they suppress the price signals that tell people what went wrong. A bad loan looks performing a little longer. An unprofitable business model survives another funding cycle. A risky balance sheet gets a second, third, or fourth life.
I have watched corporate treasurers and fund managers blow millions of dollars misreading that exact dynamic. They see a central bank or government backstop calm a market storm in weeks, assume the risk has been permanently neutralized, and double down on concentration and leverage right before the next, nastier shock hits. Calm prices do not mean healthy fundamentals. Sometimes they just mean nobody is allowed to tell the truth yet.
What Hall and Woodford Actually Built—and Where People Misread It
To critique the popular narrative fairly, we have to separate caricature from actual scholarship. Robert Hall and Michael Woodford are serious economists whose work has shaped modern macroeconomics, monetary theory, and stabilization analysis.
In standard macroeconomic parlance, stabilization policy refers to deliberate fiscal or monetary actions aimed at moderating fluctuations in output, employment, and inflation. Forward guidance—a concept closely associated with Woodford's contributions to monetary economics—involves shaping expectations about future policy paths rather than relying solely on immediate interest rate moves. Meanwhile, macroeconomic volatility measures the size and frequency of swings in aggregate economic activity, and moral hazard describes the tendency to take greater risks when protected from the full downside of those risks.
Here is the misunderstanding that creeps into everyday coverage: people hear "smoothing" and picture a magic shock absorber that removes the cost of adjustment. In reality, modern stabilization frameworks wrestle constantly with expectations, frictions, commitments, and trade-offs. Expectations matter enormously because households and firms react not just to what policy is doing today, but to what they believe policy will do tomorrow.
Yet when pundits translate complex macro models into Sunday-paper summaries, nuance gets flattened into a sales pitch for permanent intervention. The subtle constraints—credibility limits, fiscal space, inflation trade-offs, and distorted incentives—get pushed into the footnotes.
Imagine a scenario where a regional banking sector faces rising losses on commercial real estate loans. Regulators and central banks move swiftly with liquidity facilities and guarantees so depositors do not panic and credit does not freeze immediately. In the short run, the shock is smoothed. In the medium run, weak institutions may linger with impaired assets, zombie borrowers may keep operating, and healthy competitors may struggle against subsidized survival.
That is the tension the "smoothing" cheerleaders gloss over. You can smooth the surface while the foundation shifts underneath.
The Questions Everyone Is Asking—And Why They Miss the Mark
Public curiosity around crisis management tends to cluster around predictable questions. Most of them start from a flawed premise.
"Can smart policy completely prevent severe economic crises?"
No. And pretending otherwise is how you set up the next one.
Prevention requires restraint during booms, not just heroics during busts. The hardest part of macroeconomic management is never the rescue; it is taking away the punch bowl while the music still sounds great. Politically, that is brutal. Economically, it is unavoidable. Whenever policymakers promise a smooth ride in every direction, markets hear: heads we win, tails the taxpayer or future saver absorbs the drag.
"Is smoothing downturns always better than letting markets clear on their own?"
No. Pure laissez-faire liquidation has a dark history of turning manageable contractions into cascading collapses, bank runs, and deep human misery. Anyone who claims "just let everything fail" ignores how contagious financial panic can be.
At the same time, treating every market correction as a five-alarm emergency that requires blanket rescue creates a different pathology: brittle stability. Systems look calm right up until the moment they snap because weak links were never pruned. The real debate is not "rescue versus ruin." It is how much adjustment is healthy versus destructive, and who bears the cost.
"What happens when governments or central banks run out of room to smooth?"
You find out which tools were real and which ones were borrowed time.
When interest rates are constrained, balance sheets are already stretched, or inflation makes aggressive stimulus radioactive, the "smoothing" playbook hits friction. Suddenly, every lever carries a visible price tag—higher inflation, currency pressure, higher debt-service burdens, or political gridlock. A strategy that relies on endless accommodation is not a permanent shield. It is a credit line with a limit you only see when you are already overdrawn.
The Hidden Costs of Endless Cushioning
When we smooth every squall, we change behavior in ways that compound quietly.
First, risk pricing gets warped. If investors believe severe downside will always be cushioned, risk premiums compress. Assets get priced for perfection or rescue, leaving almost no margin of safety when an unexpected shock arrives—whether that shock is a supply chain break, a geopolitical flare-up, a productivity slump, or a sudden jump in borrowing costs.
Second, bad capital stays locked in place. Creative destruction sounds harsh in a textbook, yet without it, capital cannot rotate easily from dying or unproductive uses into new, high-value ones. Keep every legacy player on life support long enough, and innovation slows while balance sheets grow heavier.
Third, public trust erodes when the bill comes due. Smoothing often shifts costs across time or across groups—savers versus borrowers, younger cohorts versus older ones, taxpayers versus asset holders. When people feel the system protects insiders and asset prices first while passing costs onto wages, rents, or future budgets, economic debate turns bitter fast.
The Downside of My Own Contrarian Stance
Honesty demands owning the blind spots of pushing back against crisis smoothing.
If you lean too hard into the "let markets take their medicine" critique, you can sound detached from real people losing jobs, homes, or savings. A recession is not an abstract chart on a seminar screen. For a family facing layoffs or a small business owner watching orders dry up, a sharp contraction is a genuine crisis, not a "healthy cleansing."
There is also a real danger of underestimating tail risks. Financial systems are interconnected networks. A shock that looks contained on paper can trigger nonlinear cascades—margin spirals, liquidity freezes, confidence collapse—faster than models predict. Stepping back too far when systemic contagion is building can turn a recoverable bump into a depression.
So the contrarian critique is not a license for apathy or ideological purism. It is a warning against mistaking short-term calm for long-term health.
What Actually Works When Volatility Hits
If you run a business, manage capital, or simply want to stop getting blindsided by macro headlines, stop waiting for policymakers to make the world smooth. Build for roughness instead.
- Audit your survival math without rescue assumptions. Stress-test your cash flow, debt maturities, and customer concentration assuming zero bailouts, higher rates for longer, and slower demand. If survival depends on a policy pivot or cheap refinancing, your plan is fragile.
- Keep dry powder when everyone else calls it lazy. Cash and low leverage look inefficient during calm, rising markets. They look like freedom when liquidity dries up and distressed opportunities appear.
- Watch incentives, not just official announcements. Look at who benefits from a policy move, who pays for it, and how balance sheets respond over 12 to 36 months—not just how stocks trade in the first 48 hours.
- Separate signal from noise in economic commentary. When you read about a breakthrough, a model, or a prize-winning framework, ask what assumptions it makes and what happens when real-world politics and human greed collide with those assumptions.
Markets do not owe anyone a smooth ride, and no clever policy framework can repeal trade-offs. Build resilience before the storm, price risk like you mean it, and stop confusing a sedative with a cure.