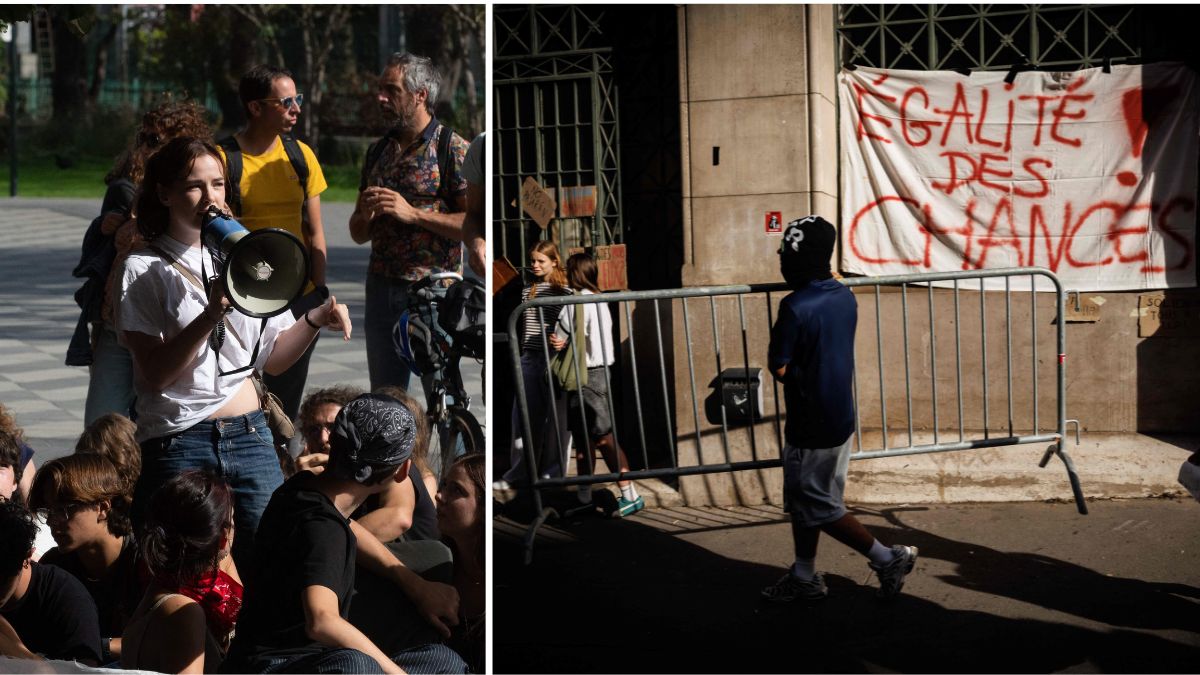
Modern urban housing crises are rarely simple manifestations of supply shortages. They are complex structural outcomes driven by regulatory misalignments, financialized real estate portfolios, and the systemic decoupling of median wages from asset valuation. When 87-year-old María del Carmen Abascal was forcibly removed from her Madrid apartment after a dramatic increase in rent following a corporate acquisition, the event functioned as a diagnostic stress test for Spain’s metropolitan economies. Rather than evaluating this eviction as an isolated legal dispute, analyzing the underlying mechanics reveals a predictable convergence of macroeconomic pressures that consistently penalize legacy tenants while maximizing yield for institutional capital.
The Tripartite Driver of Market Distortion
Urban property markets in primary European hubs operate under three distinct pressures: structural supply deficits, capital inflow from institutional investment funds, and regulatory gaps governing legacy leases.
The primary vector of pressure is the absolute supply-demand imbalance. According to estimates by the Bank of Spain, the national housing deficit exceeds half a million units, concentrated heavily within high-opportunity zones like Madrid, Barcelona, and Valencia. This undersupply is compounded by structural rigidity in new construction timelines, zoning restrictions, and the diversion of existing residential stock toward short-term tourism rentals.
The second vector involves the financialization of residential real estate. When investment funds or private equity vehicles acquire multi-family buildings, their fiduciary mandate requires yield optimization. Legacy tenants residing under historical rent protections or low contractual baselines represent a negative variance against projected asset performance. Consequently, capital allocators deploy aggressive pricing strategies—such as exponential rent adjustments or purchase ultimatums—to clear legacy occupants and capture market-rate yields.
The third vector is the regulatory asymmetry between legacy contracts and contemporary market conditions. Historical rent stabilization frameworks often lacked mechanisms to transition properties smoothly over decades, creating a binary cliff effect when ownership changed hands or exemptions expired. When the legal framework permits steep revaluations without a transitional runway, vulnerable populations experience immediate displacement.
The Cost Function of Urban Displacement
To understand why thousands of citizens mobilized across Spanish urban centers following the eviction, one must examine the cost function borne by the renter versus the return profile realized by the asset owner.
For the individual tenant, displacement from a long-held domicile incurs catastrophic switching costs. In a market where rents have surged far ahead of historical wage growth, finding alternative accommodation within a familiar social infrastructure is mathematically improbable for fixed-income pensioners. Data from European statistical frameworks indicate that lower-income Spanish renters routinely allocate over forty percent of their disposable income to housing and utilities, more than double the broader European Union average.
Conversely, the institutional balance sheet calculates this friction differently. The cost of legal proceedings and public relations backlash is treated as a variable expense weighed against the capital appreciation and cash-flow expansion of the revalued asset. When the expected net present value of the cleared unit exceeds the social penalty, market actors execute the eviction. The divergence between financial accounting and social welfare creates an irreconcilable policy tension.
Systemic Vulnerabilities and Policy Limitations
Public intervention strategies typically attempt to mitigate these frictions through rent caps, eviction moratoriums, or supply-side stimulus. However, each intervention introduces counter-regulatory effects that alter market behavior.
Rent control policies, while shielding incumbent tenants from immediate price shocks, often disincentivize maintenance expenditure by landlords and compress overall rental inventory as owners convert units to alternative uses. Meanwhile, public housing stock in Spain remains severely constrained, accounting for a fraction of total inventory compared to the European Union median, depriving municipal governments of a viable buffer to absorb displaced populations.
Without adequate public housing buffers or elastic private supply, legal protections against eviction often result in prolonged legal gridlock rather than structural resolution, leaving both property owners and tenants trapped in adversarial judicial cycles.
Strategic Allocation of Regulatory Capital
Resolving structural urban displacement requires targeted institutional adjustments rather than symbolic legislative reactions. Policymakers and market participants must address the systemic drivers through three operational interventions:
- Expansion of Publicly Backed Rental Stock: Municipalities must scale alternative housing stock via public-private partnerships to directly influence market pricing elasticity and provide immediate relocation infrastructure for vulnerable demographics.
- Graduated Transition Frameworks: Replace abrupt contractual reset clauses with mandatory multi-year glide paths for rent adjustments on legacy properties, preventing sudden shocks that outpace median pension and wage growth.
- Targeted Yield Regulation for Institutional Portfolios: Implement tiered regulatory oversight for corporate landlords holding concentrated residential assets, aligning tax incentives with long-term tenant stability rather than short-term capital appreciation.