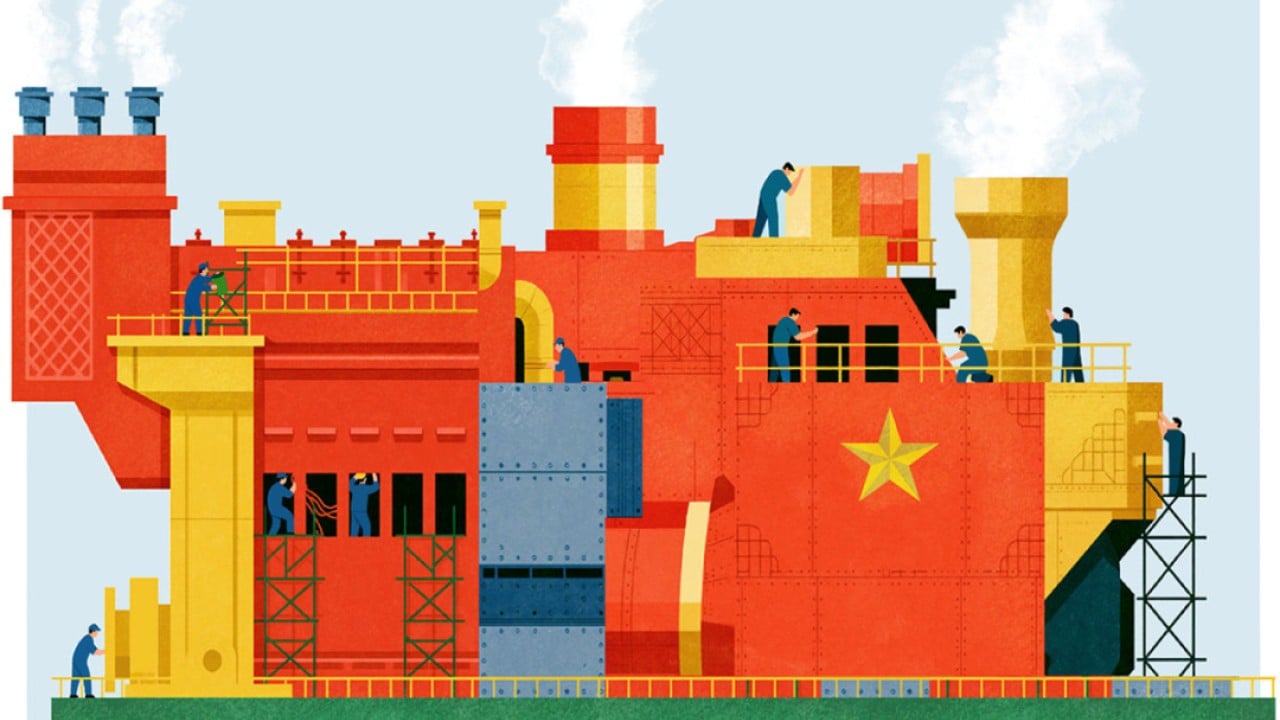
The prevailing assumption in Western trade policy rests on a fragile foundation. Washington and Brussels operate under the belief that restricting access to advanced semiconductor lithography machines, tightening silicon choke points, and slapping blanket tariffs on imported goods will break the momentum of China's manufacturing sector. Decades of reporting from industrial hubs across Guangdong, Zhejiang, and Jiangsu tell a different story. These punitive measures do not dismantle the engine; they merely force an aggressive engineering pivot that accelerates domestic self-sufficiency.
When trade restrictions block the importation of foreign components, the response from Beijing and its massive industrial conglomerates is rarely capitulation. Instead, it triggers a state-backed mobilization of capital, engineering talent, and institutional focus toward localized replacement. Tariffs treat symptoms while ignoring the structural mechanics of a supply chain that has spent thirty years optimizing for absolute scale, localized component clusters, and relentless cost reduction. For a different view, read: this related article.
To understand why trade barriers fail to stop China's industrial output, one must examine the fundamental design of modern manufacturing ecosystems. Western policymakers often view industrial might through the narrow lens of a single critical technology, such as extreme ultraviolet lithography or specialized software. If you cut off the supply of that single node, the theory goes, the entire apparatus grinds to a halt.
Reality proves far more resilient. Modern industrial production relies on deep clusters of specialized suppliers located within hours of final assembly plants. When foreign tooling or materials face sanctions, domestic alternatives receive immediate subsidization and guaranteed procurement contracts from state-owned enterprises. This localized ecosystem absorbs the shock. Engineers redesign circuit layouts, material scientists reformulate alloys, and production lines adapt. Related analysis on this trend has been published by Forbes.
Consider the evolution of domestic semiconductor packaging and legacy chip production. While headlines focus exclusively on cutting-edge three-nanometer processors, the vast majority of the global economy runs on mature nodes—the twenty-eight-nanometer and older chips that power automobiles, industrial automation, and household appliances. Export controls aimed at high-end artificial intelligence accelerators have inadvertently forced Chinese firms to corner the legacy chip market. Domestic equipment manufacturers are now producing lithography alternatives at scale, capturing global market share while Western competitors grapple with supply chain fragmentation.
The financial architecture supporting this industrial expansion differs radically from Western market models. State directed credit flows into strategic sectors with a long-term horizon that private equity markets rarely tolerate. When a factory in Shenzhen or Chengdu operates at a loss during its initial scaling phase, municipal and provincial governments absorb the balance sheet strain through equity stakes, tax holidays, and subsidized real estate.
This financial cushioning allows industrial heavyweights to sustain overcapacity without facing immediate bankruptcy pressures. Western critics label this practice unfair trade, pointing to suppressed pricing and flooded global markets for electric vehicles, solar panels, and legacy semiconductors. Yet complaints about market distortion do little to alter the underlying physics of production. Lower prices and reliable volume win market share across the Global South, where infrastructure development demands affordable technology rather than geopolitical purity.
Logistics networks further insulate the industrial base from external disruption. The expansion of rail freight corridors connecting interior manufacturing centers directly to European and Central Asian markets bypasses traditional maritime choke points. Ports along the coast operate with high degrees of automation, moving container volume at speeds that older Western facilities struggle to match.
Labor dynamics also undergo a silent transformation. As low-end assembly migrates to lower-wage nations like Vietnam or Bangladesh, domestic factories upgrade their automation profiles. Industrial robotics installations within the domestic market outpace every other region globally. Factories deploy locally manufactured robotic arms, automated guided vehicles, and machine-vision quality control systems at a fraction of the cost of imported automation hardware.
The attempt to decouple through regulation collides with the reality of commercial gravity. Multinational corporations with headquarters in New York, Frankfurt, or Tokyo cannot simply walk away from a market that constitutes both their largest consumer base and their most efficient manufacturing floor. Corporate boards face an intractable dilemma. Complying with strict export controls means sacrificing billions in revenue and ceding market share to competitors who find alternative supply pathways.
Multinationals respond by ring-fencing operations. They establish dual-track supply chains, separating products destined for Western markets from those built for domestic consumption using entirely local supply bases. This bifurcation defeats the original intent of trade sanctions. Rather than isolating the target economy, sanctions encourage the creation of parallel, self-contained supply chains that operate entirely outside Western intellectual property and financial jurisdictions.
Technical talent plays a decisive role in this resilience. Hundreds of thousands of engineers graduate annually from domestic universities, many with advanced degrees from elite institutions abroad who return home attracted by generous research grants and aggressive venture funding. This talent pool does not need to reinvent every wheel from scratch; they possess the foundational knowledge required to reverse-engineer, improve, and mass-produce complex industrial machinery.
When a restriction hits a specific sector, such as aerospace composites or chemical catalysts, it acts as a clarion call for domestic research institutes. Laboratories partner directly with manufacturers to bridge the gap between academic theory and factory floor execution. The timeline from laboratory discovery to commercial scale, which often languishes in bureaucratic delay elsewhere, moves with remarkable speed under this coordinated industrial policy.
The geopolitical messaging surrounding tariffs often frames them as a permanent defensive shield. History suggests otherwise. Protectionism without internal structural reform tends to foster complacency among domestic industries. When foreign competition is artificially suppressed, local incumbents often lose their edge. In this case, however, protectionism is being applied against an adversary that already possesses massive scale, aggressive competition among domestic players, and an uncompromising mandate for technological self-reliance.
Domestic competition within the industrial sector remains fierce. Hundreds of domestic electric vehicle manufacturers, battery producers, and robotics firms fight for market dominance inside the domestic market before expanding abroad. This internal Darwinian struggle culls weak companies while hardening survivors against external price wars and trade barriers.
When tariffs raise the cost of direct exportation to Western markets, industrial groups adapt by shifting value chains overseas. They establish assembly plants in Mexico, Southeast Asia, or Eastern Europe, routing components through third countries to navigate regulatory hurdles. The final product may carry a non-target country label, but the underlying components, machinery, and metallurgical inputs trace directly back to the same industrial engine.
The limits of financial sanctions are equally apparent. Efforts to cut specific firms out of international clearing systems or restrict access to venture capital have forced the development of alternative financial channels and digital currency pilots. While these alternative systems do not yet replace the dollar-denominated global trade architecture, they provide a growing buffer against extraterritorial economic coercion.
Western trade policy must confront a sobering truth. Industrial dominance is built on decades of accumulated know-how, deep supply chain integration, and relentless capital investment. A tariff is a tax on domestic consumers and an administrative hurdle for importers; an export control is a temporary delay for an engineering team determined to build a domestic substitute. Neither instrument addresses the underlying erosion of domestic manufacturing capacity, technical education, and industrial infrastructure in the West.
The industrial engine of the East continues to turn, fueled by state capital, engineering discipline, and a vast internal market that rewards scale above all else. Treating this dynamic as a temporary aberration or a problem solvable by executive decree misunderstands the fundamental redistribution of global industrial power.
The factories run because the ecosystem supporting them is vast, self-correcting, and deeply entrenched. As long as the engineering talent remains motivated, the capital flows uninterrupted, and the domestic market demands volume, external trade barriers will serve less as a brick wall and more as an inconvenient speed bump on the road to total industrial autonomy.