Every armchair lawyer on the internet thinks they know the golden rule of real estate. Get it in writing, or it never happened.
They are wrong. Dead wrong. And that lazy consensus is costing families hundreds of thousands of dollars in courtrooms across the country. In other updates, read about: The Quiet Retreat of Hong Kong Developers from Mainland China.
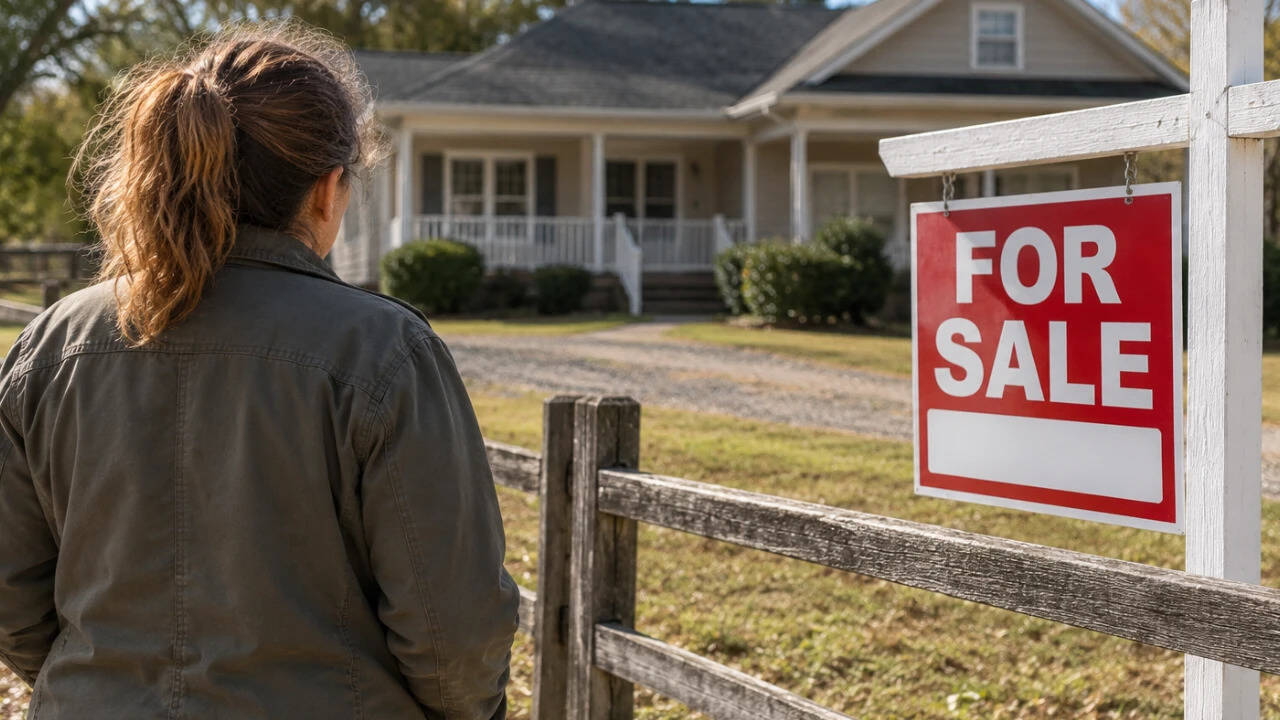
When a viral story broke about a man trying to sell his house for $150,000, only to be stopped cold because his cousin’s four-year-old verbal agreement held up in court, the comment sections erupted with predictable outrage. People screamed about the Statute of Frauds. They mocked the seller for being naive. They patted themselves on the back for knowing that real estate requires ink on paper.
Here is the uncomfortable truth those commenters missed. The court did not make a mistake. The law worked exactly as it was designed to work. If you rely exclusively on the Statute of Frauds to protect your property rights—or to screw over a relative when property values spike—you are walking into a legal buzzsaw. Investopedia has also covered this fascinating topic in extensive detail.
The Statute of Frauds Is a Shield, Not a Sword
Most people treat the Statute of Frauds like an absolute brick wall. Passed by the English Parliament in 1677 and adopted in some form by every American state, this doctrine generally requires contracts for the sale of land to be in writing and signed by the party being charged.
On paper, that sounds simple. No signature, no sale.
In practice, real estate law is riddled with exceptions built specifically to stop dishonest sellers from using technicalities to commit fraud. Courts of equity spent centuries refining a rule called part performance.
When a buyer relies on a verbal promise to buy a house, moves in, pays the mortgage, covers property taxes, or pours tens of thousands of dollars into renovations, the handshake stops being a casual chat. It becomes an enforceable contract. Judges look at actions, not just paperwork. If a cousin lives in a house for four years, maintains the roof, pays the bills, and hands over cash every month under the explicit verbal understanding that the equity belongs to them, a judge will not let the titled owner swoop in four years later and cash out at $150,000 just because the market got hot.
I have sat across the table from dozens of property investors and grieving heirs who learned this lesson the hard way. They walked into litigation convinced they held a winning hand because they possessed the recorded deed and zero signed contracts existed. By the time discovery ended, they were paying six-figure legal fees just to settle for pennies on the dollar. The paper deed meant nothing once the court examined four years of bank transfers, text messages, and hardware store receipts.
Why Family Real Estate Deals Implode
The real villain in the $150,000 cousin dispute is not the verbal agreement. It is the toxic collision of blood ties and rising home equity.
Nobody fights over a verbal deal when a house is underwater or falling apart. In fact, titled owners love informal arrangements when a property is a burden. Uncle Bob or Cousin Sarah moves in, fixes the plumbing, keeps the property from being condemned by the city, and covers the carrying costs. Everyone smiles at Thanksgiving.
Four years pass. Neighborhood values double. Suddenly, that crumbling liability is worth $150,000.
Amnesia sets in overnight. The titled owner suddenly remembers the transaction as a "month-to-month rental" rather than a "rent-to-own" or "installment sale." They hire a listing agent, slap a sign in the yard, and act shocked when the relative files a lis pendens—a formal notice of pending legal action—that freezes the title and kills the $150,000 sale dead in its tracks.
The Fatal Flaw of Half-Baked Paperwork
You might think the obvious solution is to force every family member to sign a formal, 30-page purchase and sale agreement drafted by a real estate attorney.
Try doing that at a Sunday family dinner. See how fast you get uninvited from the holidays.
Worse yet, half-baked written contracts are often far more dangerous than pure verbal agreements. When amateurs download a generic lease template off the internet to "keep things simple," they accidentally destroy their actual intent. If you verbally agree to sell your house to your brother over five years, but you sign a standard residential lease just to have "something on paper," you just handed him a weapon—or ruined his equity—depending on who sues first. The parol evidence rule generally prevents parties from bringing up prior verbal understandings to contradict a clear, written contract. A bad piece of paper locks in a lie. A pure verbal deal, backed by years of consistent financial behavior, actually gives a judge the flexibility to uncover the real truth.
Dismantling the Myths Around Verbal Property Deals
People asking questions about informal property transfers usually start from the wrong premise entirely. They ask how to void a verbal deal, when they should be asking how to prove what actually happened.
Can you really lose your house over a handshake deal?
Yes, easily. Under the doctrine of promissory estoppel and part performance, if the other party can prove three things—payment of money, physical possession of the property, and valuable improvements made to the land—most state courts will enforce the transfer of title. You do not need all three in every jurisdiction; often, possession plus significant improvements or consistent purchase payments will trigger specific performance, forcing you to sign over the deed.
Doesn't the person on the deed automatically win in eviction court?
Only if the occupant fails to raise an equitable defense. If a seller files a standard eviction action in municipal or housing court, the occupant's lawyer will immediately move to transfer the case to a higher civil court with equity jurisdiction. Housing courts handle simple landlord-tenant disputes; they cannot decide who truly owns a house. Once the case moves up, the eviction stalls for years while title ownership gets litigated.
Are text messages and emails considered a written contract?
In 2026, yes. Courts across the United States routinely treat email chains, text threads, and even direct messages as valid "writings" under the Electronic Signatures in Global and National Commerce Act (ESIGN) and the Uniform Electronic Transactions Act (UETA). If you texted your cousin, "Keep paying the $800 a month and the house is yours in five years," you did not make a verbal deal. You signed a digital contract. Your phone is Exhibit A.
How Part Performance Actually Works in Court
To understand why that cousin blocked a $150,000 sale, you have to understand how judges weigh evidence when there is no formal contract. Courts hate forfeitures. They despise watching someone invest years of sweat equity and cash into a home only to be evicted right before the finish line.
Judges look for conduct that is "unequivocally referable" to a sale agreement. That legal phrase is the entire ballgame.
Imagine a scenario where a tenant pays $1,200 a month for a house. If they paint a bedroom or fix a leaky faucet, a judge views that as normal tenant behavior. It proves nothing about ownership. Now imagine that same occupant pays $1,200 a month, drops $25,000 on a new HVAC system and a new roof, pays the annual county property tax bill directly to the treasurer, and carries homeowner’s insurance rather than renter’s insurance.
No normal renter spends $25,000 on a roof for a landlord without demanding a rent reduction. That behavior only makes sense if the occupant believed they owned the property. Once a judge sees that pattern, the Statute of Frauds evaporates. The seller’s claim that "it was just a verbal favor" collapses under the weight of basic human logic.
The Contrarian Playbook for Informal Real Estate
I will be the first to admit the massive downside of relying on verbal deals or equity doctrines: litigation is ruinously expensive. Winning a part-performance case proves you were right, right after you spend $40,000 on lawyers and wait two years for a trial date. Even when you win, you lose time, peace of mind, and family relationships.
If you are currently sitting on either side of an informal property deal—or if you plan to help a relative buy a home—stop pretending that casual trust will survive a $150,000 windfall. You do not need a sterile, corporate law firm to ruin your family dynamic, nor should you leave things to memory.
Execute these four steps immediately to protect everyone involved:
- Separate the money trail from day one. Never accept or pay cash without a digital paper trail. Every single transfer must happen via bank transfer, check, or payment app with an explicit memo line: "Installment payment 14 of 60 toward purchase of 123 Oak Street." If you are the seller and you intend it to be rent, write "Rent" on the receipt. Ambiguity is poison.
- Record a Memorandum of Contract. You do not have to put your private financial details into the public record, and you do not need a complex closing. A simple, one-page Memorandum of Option or Memorandum of Installment Sale, signed, notarized, and filed at the county recorder’s office for less than fifty dollars, puts the entire world on notice. It prevents the seller from secretly listing the house or taking out a home equity loan behind the buyer's back.
- Audit your text messages before you threaten legal action. Before any seller tries to pull the plug on a relative to grab a higher market price, search your own phone for the address of the house, the words "deed," "equity," "yours," or "payoff." If you promised the house in a moment of generosity three years ago, a forensic extraction of your messages will hand the property to your relative on a silver platter.
- Use a third-party loan servicer. For less than $35 a month, a licensed note servicer will collect the monthly payments, track the principal balance, manage the property tax escrow, and issue year-end tax statements. It removes the emotional friction of family members hounding each other for money and creates an undeniable, institutional record of a real estate sale.
The Real Lesson of the $150,000 Standoff
The commentators laughing at the man who lost his $150,000 sale missed the entire point of property law. Real estate is not a game of technicalities where the person holding the prettiest piece of paper gets to rob their family.
Courts exist to enforce the actual deal two human beings made, not the revisionist history one of them invents when prices go up. If you shake someone's hand, take their money for four years, let them build a life inside four walls, and watch them pour their savings into the foundation, that house is already sold.
The law does not care that you forgot to get a notary. Put your terms in writing today, or prepare to let a judge write them for you.